Capital gains tax is what turns a profitable property sale from a win into a calculation. Almost every major market taxes some form of profit when you sell, but the rates, exemptions, filing deadlines and definition of the taxable gain differ sharply between the US, UK, Canada and Australia. This guide explains the shared arithmetic, then shows where the rules diverge. It is an educational planning guide, not a tax return or a filing instruction: verify the current rule for your tax residence, property location, entity and tax year with the relevant authority or a qualified tax professional before acting.
Disclosure and scope
Editorial review note: Nirmal Lashkari is a real-estate publisher, not a tax adviser, CPA or lawyer. The 23 August 2026 review checked source links, dates, assumptions, calculations, accessibility and mobile readability; no professional tax credential is claimed. Use the named official authority and a qualified local professional for a real disposal.
The examples use USD for comparison only and do not predict the tax bill for a real seller. A residence exemption, cost-basis rule, holding period, marginal rate, state or provincial tax, foreign-resident rule and reporting deadline can change the result. The official links beside each jurisdiction are the place to re-check a time-sensitive claim; the article was substantively reviewed on 23 August 2026.
Tax disclaimer — read before using the examples
This is educational content, not tax, legal or filing advice. The numeric worksheets below are illustrative examples only; they deliberately omit facts that can change a real return, including state/provincial tax, Medicare or social contributions, depreciation, losses, residency, entity type, exchange rates and special reliefs. Verify the exact disposal date and taxpayer facts with the official authority and a qualified tax professional before listing, exchanging or filing.
Quick rule map — verify before you sell
| Jurisdiction | Main question | Planning signal | Official verification |
|---|---|---|---|
| United States | Is it a main home, rental or investment asset, and is the gain short- or long-term? | Home-sale exclusion, basis, federal long-term rates, NIIT, state tax and possible 1031 deferral are separate checks. | IRS Topic 409 (updated 25 February 2026) · IRS home-sale guidance · IRS like-kind exchange guidance |
| United Kingdom | Was the property your only/main residence, and is UK residential CGT due? | Private Residence Relief, the annual exempt amount, residential rates and the 60-day report/pay rule are separate checks. | HMRC HS283 Private Residence Relief (updated 6 April 2026) · Report and pay CGT |
| Canada | What inclusion-rate rule is enacted for the disposal date and taxpayer type? | Principal-residence treatment may shelter a home, but proposed or deferred inclusion-rate measures must not be treated as settled without current CRA/Finance confirmation. | CRA Capital Gains 2025 · Finance Canada announcement (31 January 2025) |
| Australia | Are you an individual, trust, company or super fund, and was the asset held long enough for the applicable treatment? | The CGT discount, main-residence exemption, cost base and foreign-resident rules are distinct; the relevant financial year matters. | ATO Capital gains tax |
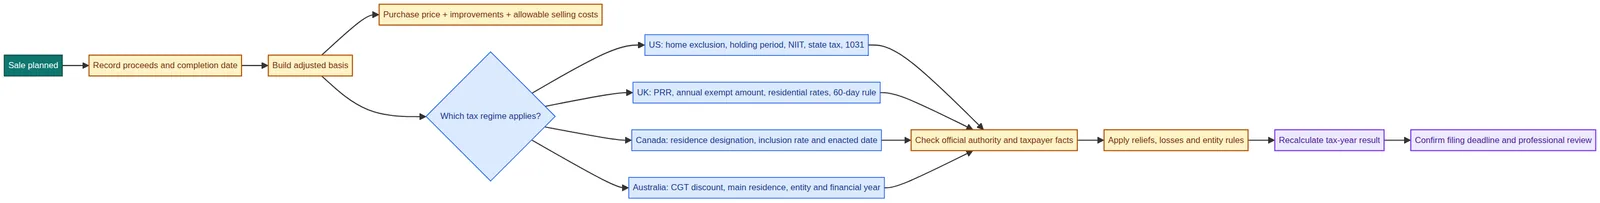
Accessible text summary of the decision flow: first record sale proceeds and the completion/disposal date; then assemble adjusted basis from purchase price, improvements and selling costs; next select the US, UK, Canada or Australia rule set; open the relevant official authority; check residence relief, losses, depreciation, holding period, entity and residency; calculate the tax-year result; and confirm the correct report, payment deadline and professional review. The diagram does not encode a rate, exemption or deadline.
How the gain is computed (the same everywhere)
The taxable gain is not simply the sale price minus the purchase price. It is the sale price minus your adjusted cost basis: the purchase price, plus capital improvements you made, plus selling costs like agent commission and legal fees, plus (in many markets) stamp duty or transfer taxes paid at purchase. Repairs count differently from improvements — replacing a roof is an improvement that adds to basis; repainting is a repair that does not — so the quality of your records directly changes your tax bill.
A worked example: buy a property for $300,000, spend $40,000 on a kitchen and bathroom renovation, and sell for $450,000 with $27,000 of agent and legal costs. Your basis is $300,000 plus $40,000 plus $27,000, or $367,000, so the gain is $83,000 — not the $150,000 that a casual subtraction of prices would suggest. The Capital Gain Calculator does the arithmetic only; it does not determine tax liability, relief eligibility or filing obligations. The Property Appreciation Calculator shows the price side of the same trade. Do not enter names, account numbers or other sensitive identifiers; see the Privacy Policy before using any online tool.
Four illustrative jurisdiction worksheets
These are four separate teaching examples, not a like-for-like international tax comparison. Each assumes an individual seller, no capital losses, no depreciation recapture, no state/provincial tax and no foreign-resident complications. The stated rate or inclusion assumption is labelled with its tax-year/check date; the result is a planning illustration, not a tax bill.
| Market and checked frame | Inputs | Illustrative calculation | Result before omitted taxes/reliefs |
|---|---|---|---|
| US — 2025 federal frame; IRS Topic 409, checked 25 Feb 2026 | Sale $450,000; adjusted basis $367,000; gain $83,000; qualifying single main home; no state tax or NIIT in this illustration | $83,000 gain − up to $250,000 home-sale exclusion when the ownership/use tests are met. Source: IRS Topic 701, checked 23 Aug 2026. | $0 federal capital-gain amount in this simplified qualifying-home example; confirm exceptions, NIIT, state tax and IRS Topic 409, checked 25 Feb 2026. |
| UK — 2025–26 residential frame; GOV.UK rates, checked 23 Aug 2026 | Sale £450,000; basis £360,000; gain £90,000; higher-rate taxpayer; no losses, local tax or residence relief | £90,000 − £3,000 annual exempt amount = £87,000; £87,000 × 24% illustrative residential rate. Source: GOV.UK CGT rates, checked 23 Aug 2026. | £20,880 illustrative CGT; confirm tax year, residence relief, exact rate and 60-day reporting guidance, checked 23 Aug 2026. |
| Canada — 50% inclusion illustration; CRA T4037 and Finance Canada checked 23 Aug 2026 | Gain C$83,000; individual; assumed 50% inclusion; assumed 45% marginal rate; no principal-residence exemption, provincial tax or proposal treated as enacted | C$83,000 × 50% = C$41,500 taxable income; C$41,500 × 45%. Source: CRA reporting guidance, checked 23 Aug 2026. | C$18,675 illustrative tax effect; do not treat the inclusion-rate proposal/deferment history as settled for every disposal. Check the 31 Jan 2025 Finance Canada announcement and current CRA rule for the disposal date. |
| Australia — individual asset held over 12 months; ATO CGT guide, checked 23 Aug 2026 | Gain A$100,000; eligible individual; assumed 50% CGT discount; assumed 40% marginal rate; no Medicare levy or entity variation | A$100,000 × 50% = A$50,000 included; A$50,000 × 40%. Source: ATO myTax CGT instructions, updated 2 Jun 2025. | A$20,000 illustrative tax effect before Medicare levy and other adjustments; entity and main-residence rules can change it. Recheck the ATO guide, checked 23 Aug 2026. |
| Shared assumptions / audit key | All four rows assume an individual seller, no losses, no depreciation recapture, no state/provincial/territory tax, no NIIT/Medicare or social contributions, no foreign-resident complication and no special relief unless stated. | Each row is a teaching calculation in the named currency and tax-year/check frame; the linked official source beside the row controls the current rule. | Illustrations are not tax bills, filing instructions or a cross-country tax comparison. |
Calculator use and privacy — arithmetic only
Before opening a calculator, confirm: [ ] I understand this tool performs arithmetic only; [ ] I will not enter names, account numbers, tax identifiers or other sensitive personal information; [ ] I will verify the result against the official authority and a qualified tax professional. The current linked tools run as browser-based arithmetic components in this site; their calculator components do not use a calculator-specific localStorage/sessionStorage write or a calculator API submission path. Results are illustrative browser output, not a tax record. The calculators do not determine tax residence, relief eligibility, inclusion rates, depreciation recapture, filing deadlines or tax liability. Review the Privacy Policy and Terms before using a tool.
- Capital Gain Calculator: estimates adjusted gain from sale price, basis, improvements and selling costs; it is not a tax-return calculator.
- Property Appreciation Calculator: models price growth only; it does not model exemptions, rates or filing obligations.
- ROI Calculator: compares investment scenarios only; it does not decide whether a 1031 exchange, residence relief or any rollover applies.
Practical filing-preparation checklist — before you sell
Use this as a preparation checklist, not a filing instruction. For every jurisdiction, save the purchase statement, improvement invoices, selling-cost invoices, completion/settlement date, ownership and residency records, prior depreciation claims, and the official page checked for the disposal date. The authority or adviser decides the correct form, return and deadline for the taxpayer type.
- US individual/resident: reconcile basis, Form 1099-S if issued, home-sale exclusion or investment classification, depreciation and state return. For a reportable capital-asset disposition, the illustrative federal path is IRS Form 8949 to reconcile sale details, then Schedule D/Form 1040 as applicable; Form 8949 was checked 30 March 2026. Non-residents, companies and trusts need separate federal/state advice.
- UK individual/resident or non-resident: record completion date, Private Residence Relief facts, annual exempt amount and allowable costs. The illustrative Self Assessment path is SA108 on the SA100 return where Self Assessment reporting applies; the separate residential-property report/pay flow and its 60-day checkpoint may also apply. SA108 was checked 13 May 2026; confirm the current tax year and taxpayer type.
- Canada individual, corporation or trust: identify the disposal-year return, principal-residence designation, inclusion rule enacted for that date, provincial tax and any deemed disposition. For an individual, CRA’s illustrative path is Schedule 3 and the taxable amount flows to line 12700; corporations and trusts use different returns. Verify the current CRA page rather than relying on a proposal summary.
- Australia individual, company, trust or super fund: identify the CGT event and financial year, cost-base records, 12-month discount status, main-residence/foreign-resident facts, Medicare levy and the correct return type. For an individual using myTax, the illustrative path is the ATO Capital gains or losses instructions, with a CGT schedule potentially required; companies and trusts use different return paths. The page was checked 2 June 2025.
Filing and reporting checkpoints — verify before completion
The dates below are navigation checkpoints, not personalized filing advice. They were checked on 23 August 2026; the disposal date, tax residence, entity and tax year control the real deadline. US state tax, Canadian provincial tax, and Australian state/local property charges can sit outside the federal CGT guidance; confirm the relevant state/provincial/territory authority as well. The table gives federal/central reporting paths only and is not a substitute for the applicable state, provincial or territory form. Open the linked official page before exchanging contracts or filing.
| Jurisdiction | What to check | Official checkpoint |
|---|---|---|
| United States — federal disposal-year frame | Example checkpoint: report the realized gain or loss on the return for the disposal year. Rental depreciation, NIIT, state tax and Section 1031 can create separate work; exact dates vary for non-residents, companies, trusts and estates. | IRS Topic 409 (checked 25 Feb 2026) · IRS Topic 701 |
| United Kingdom — residential disposal | Example deadline: report and pay UK residential CGT generally within 60 days of completion — checked 23 August 2026. Confirm Private Residence Relief and note that non-resident, company and trust obligations can differ. | HMRC report and pay guidance (checked 23 Aug 2026) |
| Canada — disposal-year return | Example checkpoint: include the taxable capital gain or loss in the relevant annual return; the exact filing/payment date varies for individuals, non-residents, companies, trusts and estates. Confirm the enacted inclusion rule for the disposal date; do not use a proposal as law. | CRA Capital Gains guidance (checked 23 Aug 2026) |
| Australia — relevant financial year | Example checkpoint: declare the CGT event in the relevant income-tax return for that financial year; exact dates vary for non-residents, companies, trusts and super funds. Check main-residence, discount and foreign-resident rules before relying on the worksheet. | ATO CGT guide (checked 23 Aug 2026) |
State, provincial and local follow-up — central guidance is not the whole bill
| Market | What the central worksheet omits | Where to start verifying |
|---|---|---|
| US | State income tax, state return/forms and local rules can change the net result; the worksheet does not model any state or non-resident withholding at closing. | Start with the official tax/revenue department for the seller’s state, then reconcile it with the IRS Form 8949/Schedule D path. Ask the closing professional whether federal/state withholding applies. |
| UK | This guide focuses on UK CGT and does not model local property charges, residency complications or entity-specific filing rules. | Start with HMRC’s current CGT and SA108 guidance; devolved administrations do not create a separate general CGT rate table for this guide. |
| Canada | Provincial/territorial tax, surtaxes, provincial filing details and non-resident withholding can change the final tax or cash available at closing; the CRA worksheet is federal/central only. | Start with the CRA Schedule 3/line 12700 guidance, then the seller’s province or territory revenue authority and closing adviser. |
| Australia | State/territory land tax, duties, foreign-resident withholding and local charges are not federal CGT and are not included in the worksheet. | Start with the ATO CGT/myTax guidance, then the relevant state or territory revenue office for land tax, duty or withholding questions. |
Calculator privacy note: the linked tools are browser-based arithmetic components in this site; this article does not ask for names, account numbers or tax identifiers, and the calculator pages link to the site Privacy Policy and Terms. Do not assume that a browser result is a tax record or that a tool determines what must be filed. Verify current data handling on the tool page before entering anything sensitive.
United States: the primary-residence exclusion
For a US main-home sale, the IRS guidance reviewed 25 February 2026 says the exclusion is generally up to $250,000 of gain for a qualifying individual or $500,000 for certain married couples filing jointly when the ownership and use tests are met; exceptions and reduced exclusions can apply. This article's worksheet omits state tax, NIIT and depreciation recapture. A rental or investment sale is a separate calculation: holding period, adjusted basis, federal long-term or short-term treatment, unrecaptured Section 1250 gain, NIIT and state tax all need checking. Start with IRS Topic 409 (updated 25 February 2026) and IRS Topic 701 on selling a home, rather than treating a headline rate as your final bill.
Some US investors may explore a Section 1031 like-kind exchange for qualifying real property. The timing and identification rules are strict, the exchange generally requires a qualified intermediary, and the result is deferral rather than forgiveness because basis carries forward. The IRS explains the requirements in its sales, trades and exchanges guidance (checked 23 August 2026); do not treat a calculator or a listing agent as a substitute for tax advice. The ROI Calculator can compare holding scenarios only; it does not determine 1031 eligibility, tax liability or filing deadlines, and users should avoid entering sensitive identifiers.
United Kingdom: residential rates and the £3,000 exemption
For UK residential property, the applicable rate, annual exempt amount and filing position depend on the tax year, taxpayer and facts. The article's 2025–26 planning frame is 18% or 24% for residential gains and a £3,000 annual exempt amount, checked against the official pages on 23 August 2026; the worksheet omits local variations and Private Residence Relief, so confirm the current figures on the GOV.UK CGT rates and allowances page before relying on them. If UK residential CGT is due, HMRC says it generally must be reported and paid within 60 days of completion; this checkpoint was rechecked 23 August 2026—use the official report-and-pay guidance and label your tax year clearly.
Your main home is protected by Private Residence Relief, which exempts the gain on a property that has been your only or main residence throughout ownership. Partial relief applies when the property was your home for only part of the period, and letting relief can reduce the bill further when part of a former main residence was rented out. The stamp duty you paid at purchase and the estate agent's fee at sale both reduce the gain, exactly as in the US example.
Canada: the inclusion rate and the principal residence exemption
IMPORTANT — Canada generally taxes a taxable capital gain through an inclusion rate rather than a standalone property-tax rate, and the result depends on the disposal date, taxpayer type, province and enacted legislation. Timeline for this guide: the Finance Canada announcement dated 31 January 2025 described a proposed change and deferred its implementation to 1 January 2026; that announcement is policy context, not proof that a rate is enacted for every seller. As of the 23 August 2026 editorial check, this guide uses only a clearly-labelled 50% inclusion assumption for teaching and does not assert a proposed rate as operative law. For a real disposal, verify the enacted rule effective on the completion/disposition date in the current CRA guidance and any later Finance Canada enactment notice—do not infer law from a proposal or press summary. Check the current CRA Capital Gains guidance (checked 23 August 2026) and the Finance Canada announcement dated 31 January 2025. The principal-residence exemption is a separate designation and reporting question, not a blanket answer for every home or taxpayer.
The practical consequence: a Canadian investor who buys a rental property, holds it, and sells realizes a real tax bill, while the same gain on a designated principal residence is usually zero. Investors who have lived in a rental at some point should weigh the principal residence designation carefully — once designated for a period, that period is protected, and the tax planning around which property to designate is genuinely worth professional advice. The Capital Gain Calculator models basis arithmetic before the inclusion rate is applied; it does not determine the enacted rate, relief eligibility or the filing result.
Australia: the 50 percent discount
Australia applies CGT through the income-tax system, and the outcome depends on the asset, taxpayer/entity, holding period, main-residence status, cost base and relevant financial year. The ATO guide checked 23 August 2026 explains that an eligible individual may receive the 50% CGT discount after the required holding period; this worksheet omits Medicare levy, entity variation and main-residence/foreign-resident complications. Use the ATO capital-gains-tax guide, which links the property, discount, cost-base and exemption guidance, rather than assuming the discount halves every seller's final tax bill.
Companies and some trusts do not qualify for the discount, and the discount applies to the gain itself, not the tax — a $100,000 gain by an individual after 12 months is taxed on $50,000. Superannuation funds get a separate two-thirds discount. As with every market here, selling costs and capital improvements reduce the gain first, so the discount applies to a smaller number than the raw price appreciation.
Depreciation recapture (US and UK angles)
For US investors, depreciation changes the exit calculation. Residential rental depreciation, adjusted basis and the unrecaptured Section 1250 portion must be reviewed together; IRS Topic 409 identifies a maximum 25% rate for unrecaptured Section 1250 gain, but the final result still depends on the asset, records, other income and transaction structure. A qualifying 1031 exchange may defer tax, subject to strict rules; it does not erase the history of the basis. Read the IRS capital-gains guidance and have a tax professional reconcile claimed or allowable depreciation before listing.
The UK has no separate depreciation recapture for residential landlords — the tax is simply the capital gain at the residential rate — but it has the mirror-image trap in reverse: renovation costs that are claimed as revenue expenses reduce your basis for capital gains purposes. The discipline in both markets is identical: track capital improvements separately from repairs from the day of purchase, because the tax office applies the distinction at sale, not at the time you spend the money. The Capital Gain Calculator accepts the improvement total as an input so the basis is right before any rate applies.
Inherited property: the stepped-up basis
Inherited property follows different rules in every market, and the differences are large. The US applies a step-up in basis: the heir's basis is the fair market value at the date of death, so decades of appreciation are never taxed. Canada applies a deemed disposition at death — the estate is treated as if the property were sold at fair market value, which can trigger a real capital gains bill, though the principal residence exemption often protects the family home. The UK uses the probate value as the basis for inheritance tax purposes with no step-up for capital gains, and Australia applies a different regime where the family home inherited by a spouse or the main residence can pass free of CGT but investment property inherited after a death triggers complex rules.
The lesson for estate planning is that the same family home produces very different sale outcomes depending on the country. None of this is a reason to avoid holding property — it is a reason to know which regime applies to your situation and to let the Capital Gain Calculator estimate the bill before the executor's deadline rather than after it.
Can you claim a capital loss on property?
Yes — in every one of the four markets, a realized loss on an investment property off sets capital gains and, where gains are insufficient, can offset other income within limits. The US allows losses to offset gains fully and up to $3,000 of ordinary income per year, carrying the remainder forward indefinitely. The UK allows losses against gains in the same or future years. Canada applies the inclusion rate in reverse: half of a loss is deductible (with the 2024 budget's asymmetry for larger amounts). Australia allows losses to offset gains with no expiry, though the 50 percent discount does not apply to losses.
The catch is that a loss must be realized — paper losses do nothing until the sale completes — and the loss calculation uses the same adjusted basis rules as a gain. Keep the same records you would for a profitable sale, because a loss is only as good as the basis arithmetic behind it. The Capital Gain Calculator handles negative gains the same way, so the loss is visible before you decide whether to sell at all.
Five questions to ask before trying to reduce the bill
- Hold past the qualifying period — the US two-of-five-years rule and Australia's 12-month discount both turn on the calendar
- Have you tested the main-residence or principal-residence conditions for the exact property, ownership period and taxpayer?
- If considering a US 1031 exchange or any rollover/deferral rule, have you checked current official eligibility and deadlines with a qualified adviser?
- Have you separated capital improvements, allowable selling costs, transfer taxes and ordinary repairs in your records?
- Would a different completion date change the tax year or marginal-rate position, and is that timing lawful and commercially realistic?
Each of these is legal, ordinary, and regularly missed. The most common mistake is the first one: selling at 11 months when the 12-month discount is a month away, or selling a US home after 1.9 years when the exclusion needs two. The ROI Calculator and Property Appreciation Calculator model the hold-versus-sell decision with the tax angle in mind, so the calendar becomes part of the trade rather than an afterthought.
Putting the same trade through all four markets
Do not compare the $83,000 worked gain as if four countries produce four directly comparable bills. The currency, tax year, residence status, marginal income, state/provincial tax, entity, deductions, losses and reporting rules differ. Use the worked example to test the shared basis arithmetic, then use the jurisdiction table and official links above to rebuild the result for the exact seller and disposal date. A neat cross-country number can create false confidence when the inputs are not like-for-like.
The same profit, four different tax bills, one identical arithmetic. Note also that the timing of the sale can move these numbers more than any single rate: selling in a year when your income is lower can drop you below the rate threshold in the US, under the higher-rate band in the UK, or into a lower marginal bracket in Canada and Australia. A married couple splitting the sale across two tax years, or a seller who waits for a year with lower income, is doing ordinary tax planning, not avoidance. If you are close to a bracket boundary and the buyer is flexible, the calendar is a legitimate lever — price it with the Capital Gain Calculator in both years before you commit to a completion date.
The same profit, four different tax bills, one identical arithmetic. That is the case for computing the gain correctly before you sell — the Capital Gain Calculator handles the basis arithmetic, and the market pages for Canada, the UK, Australia, and the USA keep the buying-side costs that feed into your basis. Tax rules change every budget cycle, so treat these rates as a planning frame and confirm the current figures for your exact situation before you sign.
Sources
- IRS — Topic No. 409, Capital Gains and Losses (updated 25 February 2026)
- IRS — Topic No. 701, Sale of Your Home
- IRS — Form 8949 and Schedule D reporting path (Form 8949 page checked 30 March 2026)
- IRS — Sales, trades and exchanges / Section 1031
- HMRC — Private Residence Relief HS283 (updated 6 April 2026)
- GOV.UK — SA108 capital gains summary for the SA100 return (updated 13 May 2026)
- GOV.UK — Report and pay Capital Gains Tax
- CRA — Capital Gains 2025 (checked 23 August 2026)
- CRA — Calculating/reporting capital gains, Schedule 3 and line 12700
- Finance Canada — inclusion-rate implementation announcement (31 January 2025; proposal/deferment context)
- ATO — myTax 2025 capital gains/losses reporting (updated 2 June 2025)
- ATO — Capital gains tax (checked 23 August 2026)
Related reading
Continue reading: Break-Even Occupancy for Landlords · How to Calculate Rental Yield (2026) · Cap Rate Explained for Investors. Run your own numbers with the Capital Gain Calculator — it takes under a minute and beats guessing.
How holding period changes the tax bill
The holding period is one of the few levers an investor fully controls, and it changes the math dramatically. In the United States, assets held over one year qualify for long-term rates of 0, 15, or 20 percent depending on income, versus ordinary income rates of up to 37 percent for short-term gains; this planning summary was checked against IRS Topic 409 on 25 February 2026. The UK's 18 and 24 percent residential rates and £3,000 allowance are the 2025–26 frame checked 23 August 2026, while the 60-day checkpoint is also date-stamped above. Australia's 50 percent discount after twelve months is the 2026 planning frame checked against the ATO guide on 23 August 2026: a gain that costs 30 percent tax after one year costs just 15 percent after two. The lesson is practical — if a deal looks marginal on price, run it through both a two-year and a ten-year exit before committing, because the tax tail can easily swing the annualised return by a full point.
- Model both exits with the Capital Gain Calculator before making an offer.
Frequently asked questions
How is capital gains tax calculated on property?
The gain is the sale price minus your adjusted basis: purchase price plus capital improvements plus selling costs (and purchase transfer taxes in many markets). Improvements like a new roof add to basis; repairs like repainting do not. The tax rate then depends on your country and holding period.
Do I pay capital gains tax on my primary residence?
In most tier-1 markets, no — with limits. The US exempts $250,000 ($500,000 married) after two of five years of residence, the UK's Private Residence Relief protects the main home, Canada's principal residence exemption covers the gain, and Australia exempts the family home.
What is the capital gains tax rate on rental property in the US?
Long-term rates of 0, 15, or 20 percent depending on income, plus the 3.8 percent Net Investment Income Tax above $200,000 for singles. A 1031 exchange defers the tax when proceeds are reinvested into like-kind property within the 45/180-day windows.
What is Australia's 50% CGT discount?
Individuals who hold an investment property for more than 12 months pay tax on only half the gain. The main residence is exempt. Companies and some trusts do not qualify for the discount.
Do improvements reduce capital gains tax?
Yes. Capital improvements add to your cost basis, which lowers the taxable gain. Keep receipts for renovations and structural work; ordinary repairs and maintenance do not add to basis and should be tracked separately.
How can property owners legally reduce capital gains tax?
The most effective levers are the primary-residence exemption (no CGT at all on your home in many countries), holding past the long-term holding period for lower rates, offsetting losses against gains, and in the US, a 1031 exchange to defer tax by reinvesting into another property. Timing the sale to a lower-income year also matters because gains stack on top of your ordinary income.